By Charles Neal October 2, 2026
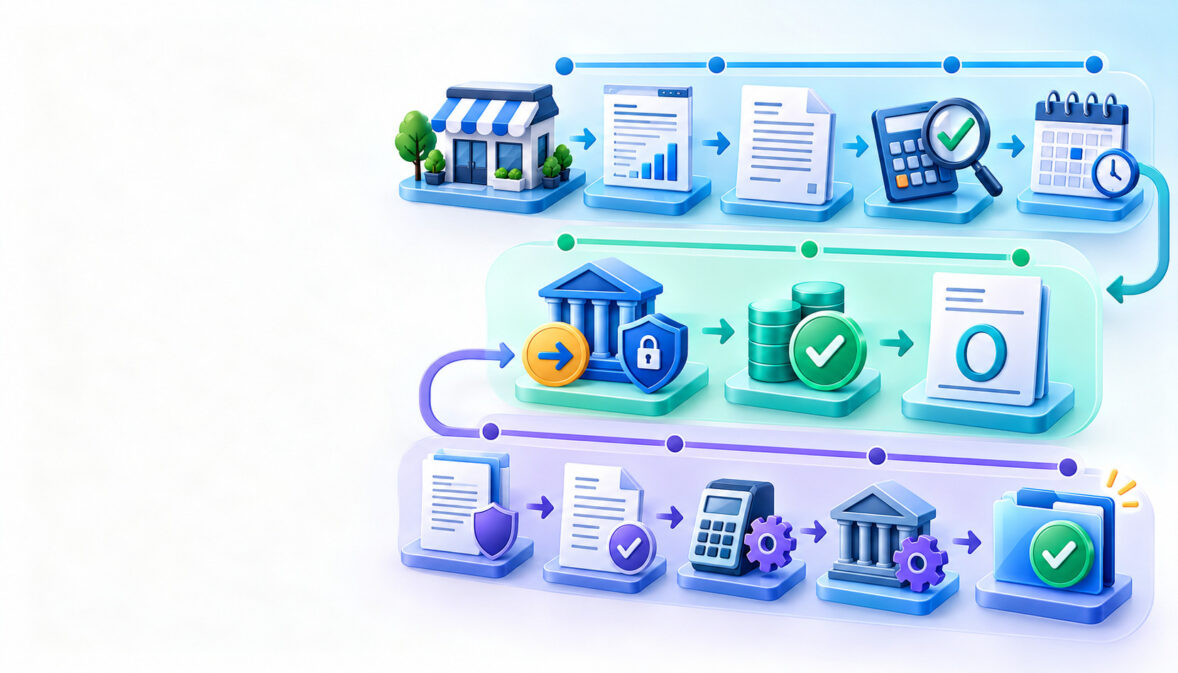
To request an MCA payoff letter, send a written request using the notice or servicing method required by your agreement and ask for the exact payoff amount, calculation date, good-through date, credited remittances, applicable fees or adjustments, verified payment instructions, UCC termination commitment, release of relevant payment-routing instructions, and post-payment satisfaction confirmation.
An MCA payoff letter is more than a balance screenshot. It is the document that should allow a merchant, refinancing funder, broker, attorney, or closing party to determine what must actually be paid on a specified date and what must happen after those funds clear.
Merchant cash advance agreements are not uniform. Some transactions are drafted as purchases of future receivables, and payoff, reconciliation, early-purchase, security-interest, ACH, processor, guarantee, and UCC provisions can differ significantly. The signed agreement therefore remains the starting point for every payoff calculation.
MCA Payoff Letter at a Glance
| Item | What the Merchant Should Look For |
| Exact payoff amount | Amount required to satisfy the transaction as of the specified date |
| Good-through date | Last date on which the quoted figure remains valid |
| Purchased amount or contractual balance | Starting figure used under the agreement, where applicable |
| Remittances credited | Payments/remittances included through a stated cutoff |
| Per-diem/per-payment adjustment | Only where the agreement or payoff method actually uses one |
| Additional fees | Itemized charges with their contractual basis |
| Payment instructions | Verified wire, ACH, or other settlement instructions |
| UCC release | Written explanation of how any UCC-3 termination will be handled |
| Processor/bank release | Treatment of applicable processor, ACH, lockbox, or bank instructions |
| Post-payment proof | Zero-balance confirmation plus available UCC filing evidence |
This table is a practical closing checklist, not a universal statutory form. The exact content of an MCA payoff statement depends on the transaction documents and applicable law.
What Is an MCA Payoff Letter?
An MCA payoff letter is a written statement from the funder or servicing party setting out the amount required to satisfy a merchant cash advance transaction as of a specified date.
Depending on the provider, the same type of document may be called a payoff statement, payoff quote, payoff demand, early-purchase quote, buyout quote, or satisfaction calculation. Those labels do not necessarily have identical legal consequences, so the substance of the document matters more than its heading.
A merchant may need an MCA payoff letter when:
- voluntarily closing an existing position;
- refinancing an MCA with new financing;
- consolidating several financing positions;
- selling the business;
- clearing a UCC filing;
- completing a transaction through escrow;
- satisfying underwriting conditions for new financing; or
- documenting that an existing MCA has been fully resolved.
When an existing advance will be paid from new financing, calculate the net new cash after the existing MCA payoff rather than comparing offers by their headline funding amounts. The portion sent to the existing funder is not new working capital available to the business.
MCA Payoff Letter vs. Monthly Balance Statement
A current dashboard balance and a formal payoff quote answer different questions.
| Document | Primary Purpose | Date Sensitive? | Future/Closing Adjustments? | Suitable for Refinance Closing? | Addresses UCC Release? | Payment Instructions? |
| Online balance | Account snapshot | Sometimes | Usually not fully | Usually insufficient alone | Usually no | Usually no |
| Periodic statement | Transaction history | Yes | Usually no | Not necessarily | Usually no | Usually no |
| MCA payoff statement | Amount needed for stated payoff date | Yes | Where applicable | Usually the relevant closing document | Should address applicable UCC filing | Usually yes |
| Zero-balance/satisfaction letter | Confirms post-payment status | After payoff | No | Useful as closing evidence | Not itself a UCC-3 | No |
A dashboard might show the provider’s internal remaining amount as of the last posted transaction. It does not necessarily tell you the amount required to close the agreement on a later settlement date.
That distinction is why a formal merchant cash advance payoff letter request should ask for a dated payoff calculation rather than simply asking, “What is my balance?”
What a Complete MCA Payoff Letter Should Show
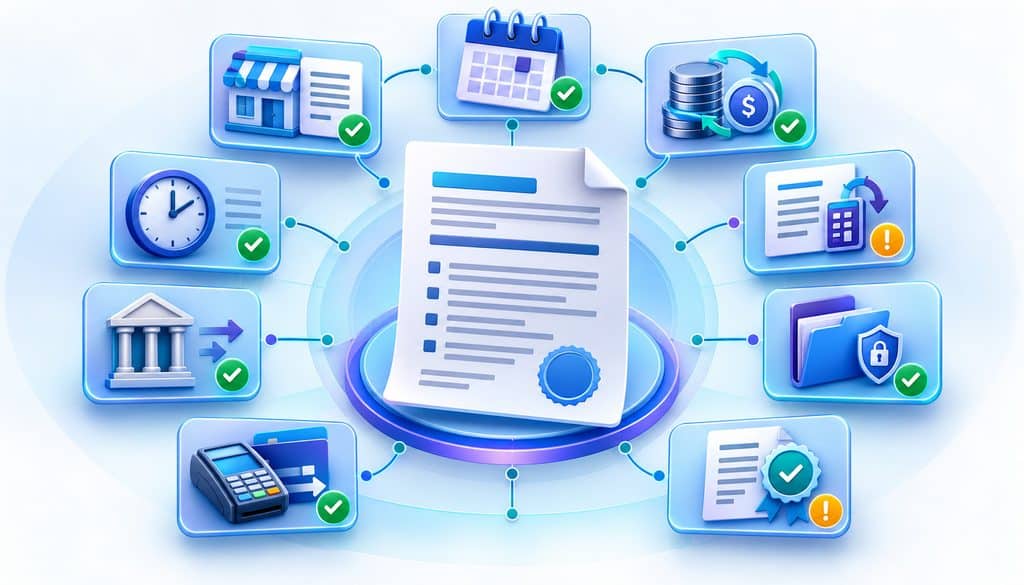
A usable MCA payoff letter should let another person reproduce or at least trace the funder’s calculation.
1. Merchant and agreement identification
Confirm:
- merchant’s legal business name;
- DBA, where relevant;
- agreement or account number;
- original funding date;
- provider’s legal name; and
- servicing entity, if different.
This reduces the risk of applying a payoff to the wrong entity or contract when the merchant has had several financing positions.
2. Calculation cutoff date
The statement should identify the date through which transactions were considered.
This matters because a remittance deducted from the merchant’s bank account yesterday may still be absent from the provider’s posted ledger today.
3. Purchased amount remaining or contractual payoff starting point
Use the terminology from the agreement.
Do not automatically relabel the figure “principal.” If the agreement is structured as a purchase of future receivables, the contractual math may not operate like an amortizing loan balance.
4. Remittances already credited
The MCA payoff statement should make clear which remittances have been included through its cutoff date.
A merchant should compare that cutoff against:
- bank statements;
- ACH records;
- processor settlement records;
- lockbox activity, where relevant; and
- the provider’s payment history.
The objective is simple: make sure recently collected amounts are neither omitted nor counted twice.
5. Contractual payoff adjustments
Depending on the signed agreement, a payoff may contain:
- an early-purchase or buyout formula;
- an early-payment discount;
- contractually defined fees;
- returned-payment charges;
- collection costs;
- reconciliation adjustments; or
- another specifically authorized calculation item.
The presence of a fee on a payoff quote does not by itself prove that the fee is contractually due.
Ask for the agreement provision supporting any amount you cannot reconcile.
Before assuming that early payoff reduces the remaining contractual cost, read the agreement’s early-payment provisions and applicable disclosures. California, for example, requires covered commercial-financing offers to describe their prepayment policies under the state’s commercial-financing disclosure framework. That disclosure requirement does not create one universal MCA payoff formula.
6. Per diem payoff amount or other update method
A per diem payoff amount is not a universal feature of merchant cash advances.
If a quote changes when payment arrives after the stated calculation date, the document should identify the method used to update the figure. Depending on the agreement, that could be:
- an amount per calendar day;
- an amount per business day;
- an amount per scheduled remittance;
- a contractual daily adjustment; or
- another defined method.
Do not automatically call a per diem payoff amount “interest.” Whether that description is legally or contractually accurate depends on the underlying transaction.
If the provider cannot explain how an expired quote should be updated, request a new payoff instead of trying to extend the figure yourself.
7. Good-through date
The good-through date answers a practical question: Until what date can the closing party rely on this payoff figure?
If the transfer will arrive after that date, obtain an updated MCA payoff letter.
Do not assume that a quote expiring Friday remains valid Monday simply because no scheduled remittance occurred over the weekend. The actual calculation method controls.
8. Payment or wire instructions
The payoff document should state:
- beneficiary/payee;
- permitted payment method;
- bank or settlement instructions, where applicable;
- account/reference information needed to identify the transaction; and
- whom to contact for confirmation.
Large payoff transfers are wire-fraud sensitive. Verify new or changed wire instructions through a known, independent contact channel before sending funds.
That verification step is prudent operational practice, not a universal MCA statute.
9. UCC filing and termination commitment
Where an MCA transaction includes a UCC financing statement, the MCA payoff letter should ideally identify:
- the debtor;
- secured party of record;
- original financing-statement number;
- filing jurisdiction;
- whether a termination will be filed or delivered after payoff;
- the conditions that must occur first; and
- what evidence will be supplied afterward.
An UCC-3 termination on payoff should never be treated as merely an administrative afterthought during refinancing.
10. Release of processor, bank, ACH, lockbox, or receivables instructions
Not every MCA involves payment-routing controls.
Where they exist, the closing process should address any relevant:
- ACH debit;
- processor split;
- lockbox arrangement;
- deposit-account direction;
- receivables direction letter; or
- processor notice.
A UCC termination does not automatically prove that every separate operational authorization has been canceled.
11. Post-payment zero-balance confirmation
The pre-payment payoff quote and post-payment confirmation are different documents.
After settlement, obtain a satisfaction or zero balance letter MCA record showing that the provider recognizes the transaction as paid or satisfied.
Keep that separate from the UCC filing acknowledgment.
Why the MCA Payoff May Be Higher Than the Online Balance
When a payoff will be deducted from renewal proceeds, even a small difference in the verified payoff changes the merchant’s usable proceeds. Calculate net new cash using the written payoff rather than the original advance balance so the comparison reflects what the business will actually receive at closing.
A higher payoff does not automatically mean the funder made an error.
The difference can have several explanations:
- different calculation cutoff dates;
- pending remittances;
- a contract-defined early-payoff method;
- fees expressly provided by the agreement;
- returned-payment charges;
- settlement-date adjustments;
- credits not yet posted; or
- a different contractual definition of “remaining amount.”
The right question is not simply, “Why is this number higher?”
The better question is: Can every dollar of the difference be traced to the signed agreement and actual transaction history?
Illustrative payoff calculation
Illustrative example only — not an industry rate or typical MCA pricing.
Assume a hypothetical agreement produces the following calculation:
- Contractual payoff starting figure: $82,000
- Less credited remittances: $11,500
- Plus documented contractual charge: $450
- Plus hypothetical date adjustment: $250
Illustrative payoff:
$82,000 − $11,500 + $450 + $250 = $71,200
None of these amounts represents a standard MCA fee, rate, discount, or per diem payoff amount.
The example shows only the reconciliation process.
How to Check the MCA Payoff Math
Before wiring funds, compare the MCA payoff statement against the agreement.
A useful conceptual worksheet is:
**Contractual payoff starting amount
− qualifying remittances already credited
± contractually authorized payoff adjustments
- documented unpaid contractual fees
= quoted payoff as of the stated date**
This is not an industry formula. The agreement determines the actual calculation.
| Item | Contract/Record Says | Payoff Letter Says | Difference | Needs Explanation? |
| Contractual starting figure | ___ | ___ | ___ | Yes/No |
| Remittances through cutoff | ___ | ___ | ___ | Yes/No |
| Early-payoff/buyout adjustment | ___ | ___ | ___ | Yes/No |
| Returned-payment or other fee | ___ | ___ | ___ | Yes/No |
| Date adjustment | ___ | ___ | ___ | Yes/No |
| Final payoff amount | ___ | ___ | ___ | Yes/No |
Use:
- signed agreement;
- amendments;
- original funding confirmation;
- transaction history;
- merchant bank statements;
- processor reports;
- previous statements;
- reconciliation correspondence; and
- current payoff quote.
If the payoff is part of a refinance, compare the replacement financing using consistent cost and cash-flow measures. A factor rate, loan APR, and line-of-credit cost cannot be compared as though they measure the same thing, particularly when the products have different payment frequencies and repayment periods.
How to Request an MCA Payoff Letter Step by Step
A good merchant cash advance payoff letter request is specific enough that the funder knows you are asking for a closing document—not an account balance.
Step 1: Read the notice and servicing provisions
Locate:
- notices section;
- designated email or physical address;
- servicing contact;
- required delivery method;
- account number;
- governing-law provision;
- dispute procedure; and
- applicable cure language.
If the agreement requires formal notices to go to a specific address, sending only an informal message to a salesperson may not satisfy that contractual requirement.
Step 2: Choose the proposed payoff date
Do not request an undated figure.
Tell the funder the anticipated refinance, sale, or settlement date and request a payoff good through that date.
Step 3: Request the calculation detail
Ask for:
- exact payoff;
- calculation cutoff;
- good-through date;
- remittances credited;
- payoff or buyout adjustment;
- individually listed fees;
- agreement provision supporting disputed charges; and
- post-expiration update method.
Step 4: Request UCC information
If a financing statement exists, ask the provider to identify the specific filing.
A UCC search may also reveal filings that no longer represent a current obligation, so a search result should be verified rather than automatically treated as proof of outstanding debt.
Before relying on a payoff to clear an existing financing position, compare it with the merchant’s UCC filing history and any other disclosed MCA positions. A filing search can identify records that need further verification, but the filing alone does not establish the current payoff amount or prove that the underlying obligation is still outstanding.
Step 5: Ask for UCC-3 termination terms
The payoff request should state that the merchant wants written confirmation of how UCC-3 termination on payoff will be handled.
Request:
- original file number;
- filing office;
- secured-party name;
- event triggering release;
- whether the secured party will file or send the termination;
- and how proof will be delivered.
Step 6: Address payment-routing releases
Where applicable, ask when ACH debits, processor splits, lockbox instructions, or receivables directions will stop.
This avoids closing the financial obligation while leaving an operational collection instruction active.
Step 7: Preserve evidence of the request
Keep:
- email copies;
- portal screenshots or confirmation numbers;
- delivery receipts;
- tracking records;
- names of contacts; and
- dates of telephone calls.
Use whatever notice method the agreement requires. Certified mail is not universally required.
Sample Merchant Cash Advance Payoff Letter Request
[Date]
Re: Merchant Cash Advance Payoff Letter Request
Merchant Legal Name: [Merchant Legal Name]
DBA: [DBA, if applicable]
Agreement Number: [Agreement Number]
Requested Payoff Date: [Requested Payoff Date]
Please provide a formal payoff statement showing the amount required to satisfy the above transaction through the requested payoff date.
Please include:
- the exact payoff amount;
- calculation cutoff date;
- good-through date;
- remittances or payments credited through the cutoff;
- any early-purchase, buyout, reconciliation, or other contractual adjustment;
- any per-day, per-payment, or other post-expiration update method, if applicable;
- an itemization of all additional fees;
- the agreement provision supporting any additional charge;
- verified payment instructions; and
- the appropriate contact for payoff verification.
If a UCC financing statement is associated with this transaction, please identify the debtor, secured party, original financing-statement number, and filing jurisdiction. Please confirm in writing the conditions and process for filing or providing the applicable termination statement after cleared payoff funds.
Where applicable, please also confirm how any processor direction, ACH debit authorization, lockbox instruction, bank instruction, or receivables direction associated with this transaction will be terminated or withdrawn following satisfaction.
After payoff clears, please provide written zero-balance or satisfaction confirmation and available evidence of the UCC termination filing.
Thank you.
This template is an operational example and is not individualized legal advice.
How Long Does a Funder Have to Provide an MCA Payoff Letter?
There is no reliable universal deadline that should be presented as an MCA-industry rule.
Three different questions must be separated.
1. What does the agreement require?
Some agreements may establish servicing procedures or response obligations.
Others may not.
Check the actual contract before asserting that the provider missed a contractual deadline.
2. Does applicable state law impose a relevant requirement?
State commercial-financing laws differ, and offer-stage disclosure rules are not automatically payoff-servicing laws.
For example, California’s commercial-financing disclosure regime requires covered offer disclosures such as total funds provided, total dollar cost, payment methodology, term or estimated term, and prepayment policy. It should not be misquoted as a universal requirement to issue every requested MCA payoff within a particular number of days.
New York likewise has detailed commercial-financing disclosure rules for sales-based financing, including calculation methods and offer disclosures. Those rules should not be transformed into an invented universal payoff-letter turnaround requirement.
3. What does the provider normally do operationally?
Operational practice is not law.
Without reliable evidence for a universal timeframe, do not state that all MCA companies produce payoff letters within “24–48 hours,” “three business days,” or “five business days.”
Request the document early enough to resolve discrepancies and verify settlement instructions before closing.
How to Challenge Charges That Do Not Appear in the Agreement
If the MCA payoff letter includes a fee you cannot identify:
- Compare it with the executed agreement and amendments.
- Request a line-item calculation.
- Ask for the section authorizing the charge.
- Reconcile every payment through the cutoff date.
- Separate arithmetic errors from contract-interpretation disputes.
- Put any objection in writing.
- Preserve documents supporting the undisputed calculation.
- Seek qualified legal advice where the amount is material or the dispute threatens a closing.
Do not simply assume the charge is enforceable because the funder listed it.
Likewise, do not declare it illegal without analyzing the governing agreement and applicable jurisdiction.
UCC-3 Termination After an MCA Payoff
This is where many payoff closings become incomplete.
Four documents should not be confused:
| Document | Function |
| UCC-1 financing statement | Public filing giving notice of an asserted security interest or covered Article 9 transaction |
| Security agreement | Underlying contractual grant or arrangement creating security rights, where applicable |
| UCC-3 amendment/termination | Filing used to amend or terminate the effectiveness of the referenced financing statement |
| Zero-balance/satisfaction letter | Provider confirmation that the account or transaction is satisfied |
A zero balance letter MCA confirmation does not itself terminate a financing statement.
Likewise, sending payoff funds does not by itself prove that the filing-office record has been updated.
What UCC §9-513 actually says
New York provides a useful example of why the common “20 days after payoff” shortcut is incomplete. Under New York UCC §9-513(c), the non-consumer provision ties the 20-day period to receipt of a signed debtor demand and specified statutory conditions. The rule therefore should not be restated as an unconditional deadline running from the date an MCA is paid.
California Commercial Code §9513 contains materially similar conditional language for non-consumer collateral: the 20-day obligation is tied to a signed demand and specified statutory conditions.
This means the correct statement is not:
“Every funder must remove the UCC within 20 days of payoff.”
The safer statement is:
The applicable state’s enacted Article 9 must be checked because termination duties depend on the transaction, the collateral, whether a qualifying demand was made, whether obligations or commitments remain, and the precise statutory language.
Who can authorize a termination filing?
This question also requires care.
New York UCC §9-509 provides that an amendment such as a termination is generally authorized by the secured party of record. It also permits debtor authorization of a termination in the specified situation where the secured party has failed to file or send a termination statement as required by §9-513 and the termination indicates debtor authorization.
Section 9-510 then provides that a filed record is effective only to the extent filed by a person permitted to file it under §9-509.
That is why a merchant should not simply prepare and submit another party’s termination statement without first establishing the legal authority to do so.
What a UCC-3 actually does
The New York Department of State identifies the UCC3 financing-statement amendment as the filing used for actions including termination. Its e-filing instructions state that termination is used to terminate the effectiveness of the identified initial financing statement with respect to the security interest of the authorizing secured party.
California’s Secretary of State likewise states that Form UCC3 is used for continuations, assignments, terminations, and amendments. Accepted filings receive an acknowledgment copy and acknowledgment letter.
Why a terminated UCC may still appear in search history
Do not promise that an old filing will “disappear” after UCC-3 termination on payoff.
California’s Secretary of State expressly explains that a termination statement generally does not change a record’s status in the index; instead, the termination is indexed to the associated filing and can appear in a debtor search. The office distinguishes that from transmitting-utility filings.
That is particularly useful operational guidance because it shows why a future underwriter may still see historical UCC records.
The merchant should therefore preserve the filing acknowledgment so it can prove what happened.
Practical UCC termination verification workflow
- Obtain the original UCC file number.
- Verify the filing jurisdiction.
- Obtain the funder’s written release/termination commitment.
- Complete payoff under the agreed conditions.
- Obtain post-payment satisfaction confirmation.
- Obtain a UCC-3 filing acknowledgment or official filing evidence.
- Search the applicable filing-office database.
- Confirm the termination references the correct initial filing.
- Retain all documents with the financing records.
The UCC-3 termination on payoff process and the contractual promise in the payoff letter should be treated as related but separate issues.
What Happens to Processor or Bank Instructions After Payoff?
A UCC termination does not necessarily cancel every payment mechanism created by an MCA agreement.
Depending on the structure, the merchant may also have:
- recurring ACH debits;
- processor-controlled remittances;
- split-settlement instructions;
- lockbox arrangements;
- receivables direction notices; or
- other deposit-routing instructions.
The MCA payoff letter should address these arrangements if they actually exist.
After funds clear, verify that applicable withdrawals or diversions stop.
Do not call every processor instruction a “lien.” A contractual collection instruction and a UCC financing statement are different legal and operational mechanisms.
Refinancing an MCA: What the New Funder or Closing Agent Needs
A refinancing funder normally needs enough information to determine exactly how much must be reserved to retire the existing position.
Relevant closing documents can include:
- current payoff quote;
- good-through date;
- update formula, if applicable;
- verified payoff wire instructions;
- original UCC filing details;
- termination commitment;
- instructions for obtaining a refreshed payoff;
- servicing contact;
- processor/bank release information; and
- post-payment evidence requirements.
How a coordinated MCA payoff can work
A transaction may proceed like this:
- New financing receives final approval.
- Existing MCA payoff statement is obtained.
- Closing party verifies the quote and payment instructions.
- Part of the new financing is reserved for the existing position.
- Existing provider receives payoff directly where the transaction calls for it.
- Receipt and cleared funds are confirmed.
- Zero-balance/satisfaction evidence is obtained.
- Applicable UCC and payment-routing release steps are completed.
- Remaining permitted proceeds are disbursed.
Not every refinance uses escrow or direct payoff. The structure depends on the parties and agreement.
What If the Funder Delays or Refuses to Provide the Payoff?
Do not jump immediately to litigation threats.
Use a documented escalation sequence.
Level 1: Repeat the request using the contract’s notice method
Reference:
- merchant name;
- account/agreement number;
- requested payoff date;
- prior request date; and
- specific documents needed.
Level 2: Escalate through servicing contacts
Depending on the provider, this may involve servicing, account management, collections, legal, or another escalation contact.
Those department names are not universal.
Level 3: Send a documented written demand
Explain that a pending refinance, sale, or closing requires a usable payoff figure.
Keep the request factual and specific.
Level 4: Review contractual dispute procedures
Check:
- governing law;
- notice requirements;
- cure provisions;
- arbitration clauses;
- forum-selection language; and
- litigation venue.
Level 5: Seek qualified counsel
Legal review becomes particularly important if:
- unexplained charges are substantial;
- withdrawals continue after claimed satisfaction;
- the funder disputes UCC release obligations;
- multiple secured parties claim interests;
- a business sale or financing closing is being blocked; or
- arbitration or litigation is being considered.
MCA Payoff Closing Checklist
Before requesting payoff
- Signed MCA agreement
- All amendments
- Payment/remittance history
- Bank statements
- Processor reports where applicable
- Existing UCC search
- Proposed payoff date
Before sending funds
- Current MCA payoff letter
- Correct merchant/agreement details
- Valid good-through date
- Calculation reconciled
- All fees explained
- Update method understood
- Wire/payment instructions verified
- UCC filing identified
- Termination commitment obtained
- Processor/bank release addressed
After sending funds
- Proof of transfer
- Confirmation funds cleared
- Zero balance letter MCA or satisfaction letter
- Scheduled debits stopped where appropriate
- Processor instructions removed where applicable
- UCC-3 filing evidence obtained
- Official filing record reviewed
- Closing documents archived
Real-World Refinance Example
Illustrative example — not a representation of any specific funder’s practices.
A merchant plans to replace an existing MCA with new business financing.
Its online dashboard shows $64,000 remaining. The formal payoff quote shows $66,100.
Instead of assuming the extra $2,100 is wrong, the merchant checks the dates.
The dashboard is based on activity posted through Monday, while the payoff is calculated through Friday’s proposed closing date. Two recently debited remittances have not yet appeared in the payoff history.
The merchant then finds an additional fee.
It asks the provider for the agreement provision supporting that charge and requests an updated reconciliation showing the missing remittances.
The closing moves to the following Tuesday, so the merchant does not reuse Friday’s expired quote. It obtains a revised MCA payoff letter for the new date.
The refinancing closing party verifies the payoff instructions through an established contact and sends the required funds.
Once the provider confirms cleared funds, the merchant obtains:
- payment receipt;
- satisfaction letter;
- termination confirmation for the identified UCC filing;
- filing acknowledgment once available; and
- written confirmation that the processor direction associated with the agreement has been withdrawn.
The merchant has now documented both sides of the closing: money paid and restrictions released.
Frequently Asked Questions
What is an MCA payoff letter?
An MCA payoff letter is a written statement identifying what must be paid to satisfy an MCA transaction as of a specified date. A strong payoff letter also identifies the calculation cutoff, good-through date, applicable adjustments, payment instructions, and relevant UCC or payment-routing release steps.
How do I make a merchant cash advance payoff letter request?
Send the merchant cash advance payoff letter request through the notice or servicing channel required by the agreement. Ask for a formal payoff good through your expected closing date and request the calculation, fees, update method, payment instructions, and release commitments in writing.
What should an MCA payoff statement include?
An MCA payoff statement should identify the merchant and agreement, exact payoff, calculation cutoff, remittances credited, good-through date, applicable contractual adjustments or fees, settlement instructions, and relevant post-payoff release obligations.
What does “good through” mean on an MCA payoff letter?
It indicates the date through which the quoted payoff amount is intended to remain valid under the terms of the statement. If settlement occurs later, obtain an updated figure unless the quote expressly provides a reliable update method.
What is a per diem payoff amount?
A per diem payoff amount is a daily amount used to update certain payoff calculations. It is not present in every MCA and should be traced to the agreement or payoff methodology before being characterized as interest or another type of finance charge.
Why is my payoff higher than my online balance?
The two figures may use different cutoffs, contain pending remittances, apply a contractual buyout formula, include authorized charges, or calculate through a later closing date. Reconcile every difference rather than assuming either figure is automatically correct.
Do I automatically receive a UCC-3 after paying off an MCA?
Not necessarily in the manner or timeframe a merchant might assume. The applicable state’s Article 9, the type of collateral, any qualifying demand, the remaining obligations or commitments, and the transaction documents all matter. Obtain written termination terms before closing and proof afterward.
The Cleanest MCA Payoff Is Fully Documented
A complete MCA payoff letter process is not just about learning one number.
Before sending funds, the merchant should know:
- how the payoff was calculated;
- which remittances were credited;
- why each additional charge appears;
- when the quote expires;
- how an expired quote changes;
- where payment must be sent;
- what will happen to any UCC filing;
- what will happen to processor or bank instructions; and
- what documentation will prove the transaction is closed.
The most reliable closing file therefore contains the signed agreement, payoff calculation, payment confirmation, post-payment satisfaction evidence, and applicable UCC and operational release records.
That gives a future funder, buyer, attorney, accountant, or underwriter something much stronger than “the MCA should be paid off.” It gives them a verifiable transaction history showing exactly what was paid and how the old position was closed.